6 Best Global Payout APIs October 2026

The best global payout API pays each payee in their local currency over real-time rails, with no instant-payout surcharge or daily cap, and any payouts API capped at 46 or 50 countries forces you to stitch together extra vendors. Paying people across borders also raises currency conversion fees and murky FX markup practices, on top of the question of settling funds in a payee's local currency instead of your own domestic currency. This guide focuses on tools that let businesses pay out in a payee's local currency without manual conversion steps.
The wrong choice means delayed settlements, manual compliance work, and margins that shrink every time you convert currency. With global payment revenue growth, choosing the right infrastructure matters more than ever. FedNow, the Federal Reserve's instant payment service, passed a participation milestone of 1,000 participating financial institutions, a sign that real-time rails are now a baseline expectation for payees. We ranked the top global payout APIs by geographic coverage, payment speed, rail diversity, and transparent pricing so you know exactly what you're getting before you integrate.
TLDR:
- Global payout APIs automate international disbursements across multiple rails and currencies
- Dots supports 300 payment rails in 190 countries, with RTP (Real-Time Payments) and FedNow settling in seconds
- Stripe limits instant payouts to 10 transactions daily across just 46 countries
- Tipalti and Trolley require 4-8 weeks to launch vs. under 1 week with Dots
What Is a Global Payout API?
A global payout API is a developer tool that lets businesses send mass international payments by connecting your software directly to payment infrastructure that automates global disbursements.
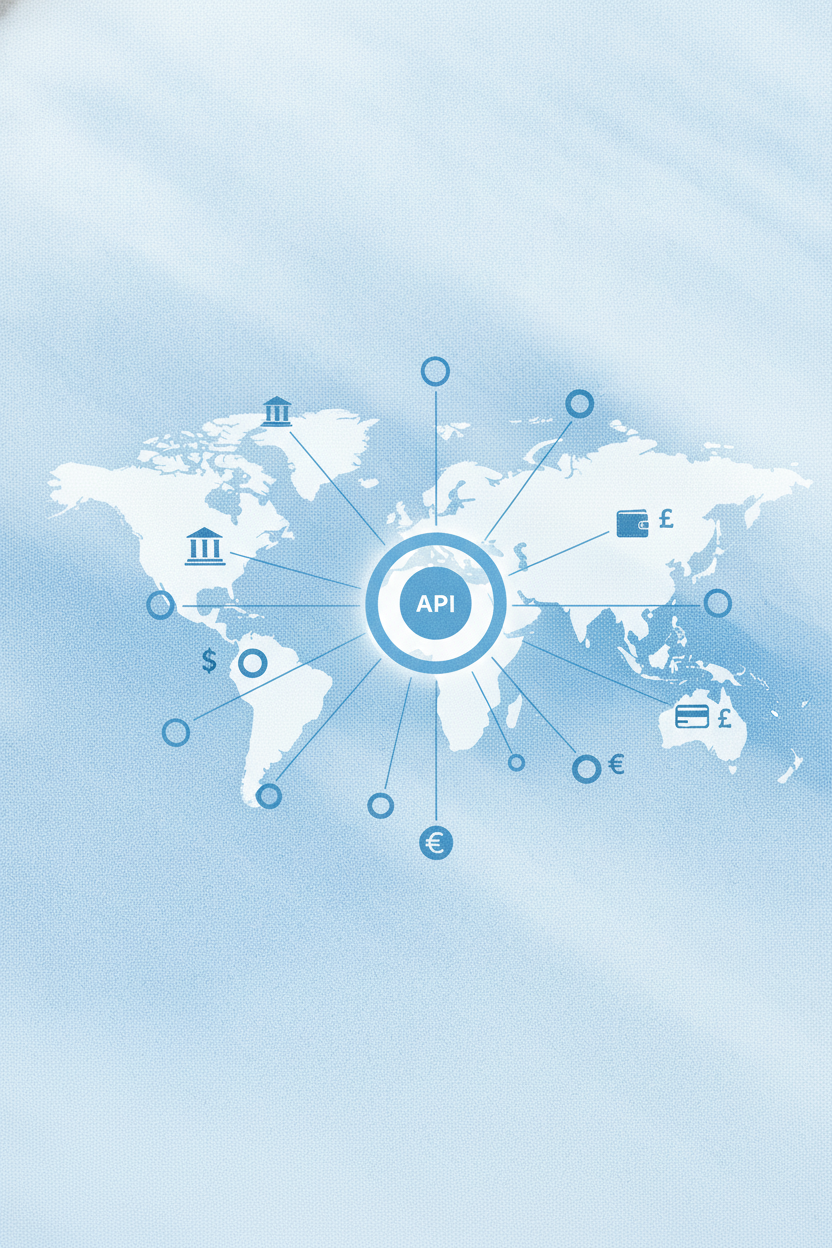
These tools take on the heavy lifting behind the scenes. They route funds through multiple rails, calculate currency conversions, and manage local compliance requirements. Encryption and tokenization protect payee bank details during transmission, while fraud detection screens each payee against global watchlists before funds move.
Automated checks such as KYC (Know Your Customer) and AML (Anti-Money Laundering) screening, plus local tax form collection like W-9s (US tax identification forms) for US payees and W-8BENs (foreign status certification forms) for non-US payees, cut regulatory risk across jurisdictions. Dots Onboard handles KYC and tax form collection as part of this process.
This cuts manual data entry and reduces costly errors. You accelerate payment speed and scale operations easily. Instead of juggling multiple banking relationships and payment processors across different regions, you connect once and access every rail you need. This unified approach means faster settlements for your payees, lower team overhead for your team, and transparent pricing that protects your margins as you scale internationally.
Signs You're Ready for a Global Payout API
Here are five signals that your current setup can no longer keep pace:
- Rising volume makes manual CSV uploads error-prone, such as a 2,000-row file where one wrong account number delays an entire batch.
- You're expanding into new countries with local compliance rules and tax-form requirements that your team cannot track by hand, a challenge our cross border money transfer guide covers in detail.
- Inconsistent payment timing hurts payee trust and drives up support tickets asking where a payment went.
- Your finance team spends hours each week matching payout records against bank statements by hand because multiple bank relationships produce separate reports. Automated payouts with real-time reconciliation replace that weekly matching and close the books faster.
- Payees ask for faster or local payment methods that your current setup cannot offer.
How Global Payout APIs Work
A global payout API moves funds from your app to a recipient in four stages, each handled by the infrastructure behind the scenes. Dots runs every stage below so you connect once and reach any payee in 190+ countries.
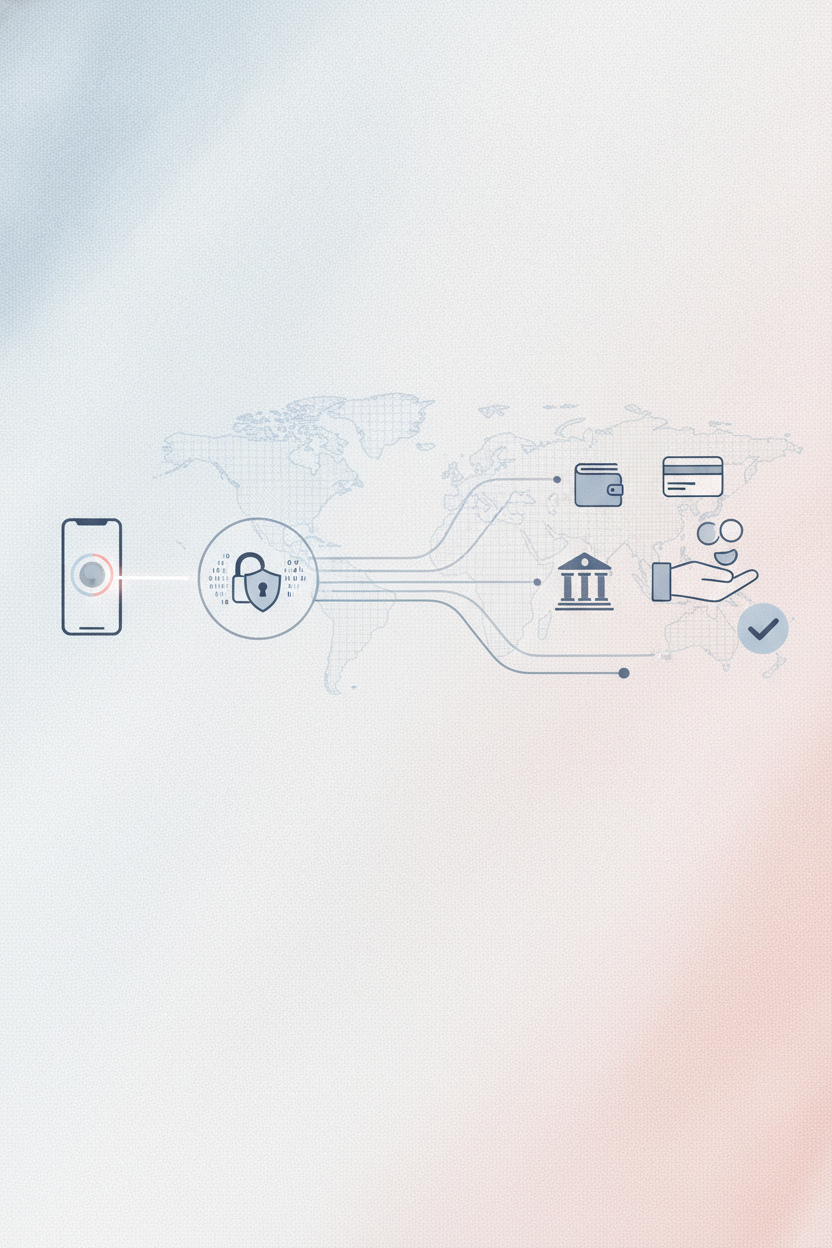
- Step 1: Transaction Initiation. Your app sends payer and payee details, the amount, and the currency to the API. For example, a marketplace paying a seller in Brazil submits a request for 480 BRL, and Dots validates the payee record before any funds move.
- Step 2: Data Security. The API encrypts data in transit and tokenizes bank details so raw account numbers are never exposed to your servers. Dots stores payee banking information in tokenized form, which keeps sensitive data out of your systems entirely.
- Step 3: Routing and Processing. A payment rail is the network that moves money between accounts, such as ACH, RTP, FedNow, PIX, UPI, or SEPA. The API picks a rail based on currency, cost, and speed for the destination country. Dots applies jurisdiction-aware routing across 300 payment rails, sending a Brazilian payout over PIX (Brazil's instant payment system), an Indian payout over UPI (India's Unified Payments Interface), and a European payout over SEPA (Single Euro Payments Area), each the lowest-cost option for that corridor.
- Step 4: Authorization and Settlement. The last stage clears the funds and confirms delivery back to your app. Dots settles through RTP (Real-Time Payments) and FedNow (the Federal Reserve's instant payment service) in seconds, routes standard ACH (Automated Clearing House) transfers in under 24 hours, and reports every status change through real-time webhooks.
How We Ranked Global Payout APIs
To help you pick a global payout API, we built an objective framework using public data. We reviewed vendor documentation, checked customer implementations, and verified published pricing. For a wider vendor list, see our top payout API providers roundup. Here are the exact ranking criteria we used:
- Geographic coverage across supported countries and currencies.
- Payment rail diversity comparing real-time networks like RTP (Real-Time Payments), FedNow (the Federal Reserve's instant payment service), UPI, and PIX to standard ACH and wire transfers.
- Settlement speed measuring time from initiation to final clearance.
- Transparent pricing including FX markups, instant-payout fees, and setup costs.
Best Overall Global Payout API: Dots
We built Dots as a developer-first global payout API to help you move money instantly. The Dots Payouts API gives you one integration for real-time and local bank rails. Our infrastructure supports over 190 countries and 150 currencies across 300 payment rails.
What We Offer
- Access ACH, RTP, FedNow, PayPal, Venmo, and digital wallets through a single integration.
- Send funds in seconds over RTP and FedNow, clear standard ACH in under 24 hours, and settle wire transfers within the same business day. You maintain full visibility with real-time status webhooks that track every payout from initiation to final settlement. This eliminates the guesswork and manual follow-up that plague legacy payment systems.
- Pros:Cons:
- 190+ countries and 300 payment rails through one integration
- Real-time rails with no instant-payout surcharge or daily cap
- Most teams go live in under a week
- A developer-first API suits teams with engineering resources better than finance teams wanting invoice approval workflows
- Dots pricing combines a monthly fee with flat domestic fees and percentage-based international fees, so model your expected international volume against the percentage fee before committing
Tremendous
Tremendous is a rewards API that specializes in distributing incentives and payouts through digital gift cards, prepaid Visas, and PayPal payments across 200 countries. Their service focuses on delivering rewards at scale for research studies, referral programs, and customer loyalty initiatives. You can send bulk funds through their API and track delivery in real time, making them a solid choice for businesses that value recipient flexibility over traditional bank transfers.
Tremendous shines when your use case is consumer rewards instead of contractor payments or vendor disbursements. Their strength lies in the breadth of redemption options (over 1,000 reward choices), which lets recipients pick what works best for them instead of forcing a single payout method. For example, a market research team running a multi-country survey can send a $25 incentive to each participant as a digital gift card chosen for that participant's country.
What They Offer
- Over 1,000 reward choices like Amazon gift cards.
- More than 2,000 payout methods including ACH.
- Automatic currency conversions for international rewards.
Pros:
- Over 1,000 reward options give recipients the choice of what fits them best.
- Digital rewards land instantly after a payout is sent.
- Coverage spans 200 countries for reward distribution.
Cons:
- Built around incentive distribution, so it suits contractor or vendor payments less well, as our Dots and Tremendous payout API comparison shows.
- Venmo, PayPal, Cash App, digital wallet, and bank transfer payouts carry a 4% to 6% sending fee.
Routable
Routable acts as an accounts payable automation tool built to manage business disbursements to vendors and contractors. It reaches 220+ countries and territories. You gain workflows for payee onboarding, tax collection, and multi-rail payments through a centralized global payout API. For example, a finance team can approve a vendor invoice and pay it by ACH or wire once the vendor's W-9 and banking details are on file.
What They Offer
- ACH, wires, virtual cards, and checks alongside invoice capture and approval routing.
- Custom onboarding flows that gather payment details and track relevant tax forms.
- Pros:Cons:
- Invoice capture and approval routing in one place.
- Payee onboarding with tax form tracking.
- ACH, wires, virtual cards, and checks.
- No real-time settlement option.
- 4 to 8 weeks to set up due to AP workflow customization and accounting sync.
- 1% to 3% FX markup on cross-border payments.
Stripe
Stripe provides payment infrastructure to route funds. They operate in 46 countries, which works locally but restricts your global payout api reach. A US marketplace paying sellers across those 46 countries through Connected Accounts can offer instant debit-card payouts for sellers who want funds the same day.
What They Offer
- Route payouts using a Connected Account setup and webhook notifications.
- Send instant payouts to debit cards with a 1% to 1.5% instant-payout surcharge, separate from the 1% to 2% FX markup on currency conversions.
- Hit a strict 10-transaction daily limit for instant transfers.
- Pros:Cons:
- Simple Connected Account setup paired with webhook notifications.
- Launch in about 1 to 2 weeks.
- Instant debit-card payouts on offer.
- Coverage limited to 46 countries.
- Instant payouts capped at 10 transactions per day.
- A 1% to 1.5% instant-payout surcharge applies, separate from the 1% to 2% FX markup on conversions.
Tipalti
Unlike Dots, which is payout infrastructure and not AP automation, Tipalti functions as an accounts payable suite. It bundles mass disbursements with invoice management and tax compliance features. For example, a finance team can run a monthly batch of supplier invoices through approval workflows that sync directly to NetSuite.
What They Offer
- An AP dashboard with approval workflows and CSV uploads.
- Payment routing across 50 rails, including ACH and PayPal.
- Direct integrations for NetSuite, QuickBooks, and Oracle.
- Native tax forms and preparation of 1099s (US forms reporting payments to non-employees).
- Pros:Cons:
- Approval workflows suit finance teams managing vendor sign-off.
- Direct connections to NetSuite, QuickBooks, and Oracle.
- Built-in tax forms cut manual 1099 prep work.
- Enterprise setup takes 4 to 8 weeks to launch.
- Batch processing only, with no real-time settlement option.
- Cross-border vendor payments carry a 2% to 3% FX markup.
Trolley
Trolley routes bank transfers across 210 countries. This tool packages multi-currency features and batch processing for your global payout api needs. A content network paying freelance writers in dozens of countries by bank transfer, for example, first collects W-8BEN (foreign status certification) forms from each writer before sending funds.
Available Features
- Bank transfers and wires reaching 210 countries globally.
- Built-in tax tools managing W-9, W-8, and 1099 collection.
- Custom portals letting payees update their own banking details, tax information, and payment preferences. This self-service approach reduces your team's administrative overhead while keeping payee data current across all transactions.Pros:Cons:
- Reaches 210 countries through bank transfers and wires.
- Built-in tax form collection for W-9, W-8, and 1099 needs.
- Self-service portal keeps payee banking and tax details current.
- No real-time settlement for payouts.
- Setup takes 4 to 8 weeks for portal and compliance work.
- 1% to 3% markup on international bank transfers.
Feature Comparison Table of Global Payout APIs
Picking the proper global payout API determines your international scaling speed and smooth operations. A poor choice traps your team with delayed settlements and high foreign exchange fees. Review the comparison below to see how Dots measures up against other options in categories like transfer speeds, setup time, and hidden costs.
Feature | Dots | Tremendous | Routable | Stripe | Tipalti | Trolley |
|---|---|---|---|---|---|---|
Countries Supported | 190+ countries with access to local payment methods and currency conversion | 200 countries focused on digital gift cards and prepaid options | 220+ countries with vendor and contractor payment focus | 46 countries limited to regions where Stripe Connect operates | 196 countries with AP automation and invoice management | 210 countries with bank transfer and wire capabilities |
Payment Rails | 300+ rails including RTP, FedNow, ACH, wires, PayPal, Venmo, and digital wallets | 2,000+ redemption methods including gift cards, prepaid Visas, and PayPal | 50 rails covering ACH, wires, virtual cards, and paper checks | ACH, wire transfers, and instant debit card payouts with daily limits | 50 rails with AP-specific methods and accounting integrations | ACH, wire transfers, and local bank networks for international contractors |
Real-Time Settlement | Yes, clears in seconds using RTP and FedNow networks | Yes, instant digital reward delivery for gift cards and prepaid options | No real-time settlement, standard processing times apply | Yes, but limited to 10 instant payouts per day with premium fees | No real-time settlement, batch processing for AP workflows | No real-time settlement, standard bank transfer timing |
Setup Time | Under 1 week to go live with full API access | 1-2 weeks for rewards program integration and configuration | 4-8 weeks due to AP workflow customization and accounting sync | 1-2 weeks for Connected Accounts setup and compliance review | 4-8 weeks for enterprise AP implementation and ERP integration | 4-8 weeks for contractor onboarding portal and compliance setup |
Instant Payout Fee | Included at no additional charge for real-time rails | Varies by redemption method, typically built into reward cost | Not applicable, no instant payout option available | 1% to 1.5% surcharge on top of standard processing fees | Not applicable, batch processing only | Not applicable, no instant payout option available |
FX Markup | Transparent pricing with no hidden currency conversion fees | No published FX markup, with a 4% to 6% sending fee on Venmo, PayPal, Cash App, digital wallets, and bank transfers | 1% to 3% markup depending on currency pair and volume | 1% to 2% markup above mid-market rates for conversions | 2% to 3% markup on cross-border vendor payments | 1% to 3% markup on international bank transfers |
Best For | Global marketplaces and gig economy apps requiring fast, scalable payouts | Research teams and loyalty programs distributing consumer incentives | Enterprise finance teams automating vendor payments and invoice approvals | Regional e-commerce businesses with limited international payout needs | Large companies managing complex AP operations with ERP systems | Businesses paying remote contractors across many countries |
Why Dots Is the Best Global Payout API
Choosing a global payout API often forces frustrating compromises. Competing options restrict your reach to 46 or 50 countries, route funds through slow ACH networks, and require four to eight weeks for setup. You also lose margins to hidden 1% to 3.5% foreign exchange markups.
Dots combines over 300 payment rails across 190 countries with real-time settlement that clears in seconds on RTP and FedNow, while standard ACH clears in under 24 hours. You get transparent pricing without hidden FX markups or instant-payout surcharges that erode your margins. Our infrastructure launches in under a week, so you can start sending international payments immediately instead of waiting months for complex implementations. (Dots)
Final Thoughts on Finding Your Global Payout API
The right global payout API connects to 300 payment rails across 190 countries without the coverage gaps and slow ACH routing that hold back regional solutions. We created Dots to give you instant payouts without setup delays or hidden FX markups. Talk to our team to see how quickly you can start moving money internationally.
FAQs
Which global payout API is best for sending payments to over 100 countries?
Dots covers 190+ countries with 300 payment rails, while Trolley reaches 210 countries but with fewer rail options. Stripe limits you to 46 countries, making it suitable only for businesses with regional needs.
Can a global payout API pay recipients in their local currency?
Dots supports 150 currencies across 190+ countries and routes payouts through local rails such as PIX in Brazil, UPI in India, and SEPA in Europe, so payees receive funds in their own currency without a manual conversion step. Before you commit to a provider, check its FX markup, since the options in this guide range from 1% to 3.5% on cross-border payouts.
How do I choose between a payout API and an accounts payable service?
Pick a payout API like Dots or Tremendous if you need speed and developer integration for contractor payouts or marketplace payments. Choose an AP service like Tipalti or Routable if you need invoice management and accounting system sync for vendor payments.
What's the difference between instant payouts and standard ACH transfers?
Instant payouts clear in seconds using real-time rails like RTP, FedNow, or UPI. Standard ACH takes 1-3 business days and costs less upfront but may carry hidden FX markups ranging from 1% to 3.5%.
Can I avoid the 1% to 1.5% fee for instant transfers?
Yes. Dots includes real-time rails like RTP and FedNow at no extra instant-payout surcharge, while Stripe charges 1% to 1.5% on top of standard fees for instant debit-card transfers.
When should I switch from my current payout provider?
Switch if you're expanding beyond 50 countries, hitting daily transaction limits on instant payouts, paying more than 2% in FX fees, or waiting longer than two weeks to go live.
Does a global payout API handle compliance like KYC and tax forms for international payees?
Dots Onboard handles KYC (Know Your Customer) screening and tax form collection, including W-9s for US payees and W-8BENs for non-US payees. For India-specific payouts, Dots Onboard also automates PAN (Permanent Account Number) collection and TDS (Tax Deducted at Source) requirements, cutting manual compliance work for your team.